Key takeaway
- Blockchain for insurance: 10 use cases from claims to reinsurance, what regulators say, the limits and risks, and when a plain database is better.
Where does blockchain fit in insurance?
Blockchain suits insurance where several parties, such as insurers, reinsurers, brokers and regulators, need one shared record that none of them can quietly edit. NIST Internal Report 8202 (October 2018) describes blockchains as distributed ledgers, usually without a central controller, in which a published transaction cannot be changed under normal operation of the network. The NAIC (US state insurance regulators) lists claims management, fraud prevention, proof of insurance and parametric cover among the uses, and also states that blockchain applications are not currently widely used in the insurance industry.
So treat it as a targeted tool, not a replacement for core policy systems. The ten use cases below show where a shared ledger can help and where it cannot. For platform choices, see our blockchain platforms comparison and enterprise blockchain guide.
What problems in insurance can a shared ledger address?
Insurance runs on documents passed between organisations: applications, proofs of identity, claims evidence and reinsurance records. Each party keeps its own copy, so reconciling them takes time and invites errors and disputes. A shared, append-only ledger gives every permitted party the same version of an event, with a history of what was recorded and when. The NAIC page notes that records written to a blockchain are permanent and cannot be deleted, which it links to audit trails and fraud reduction.
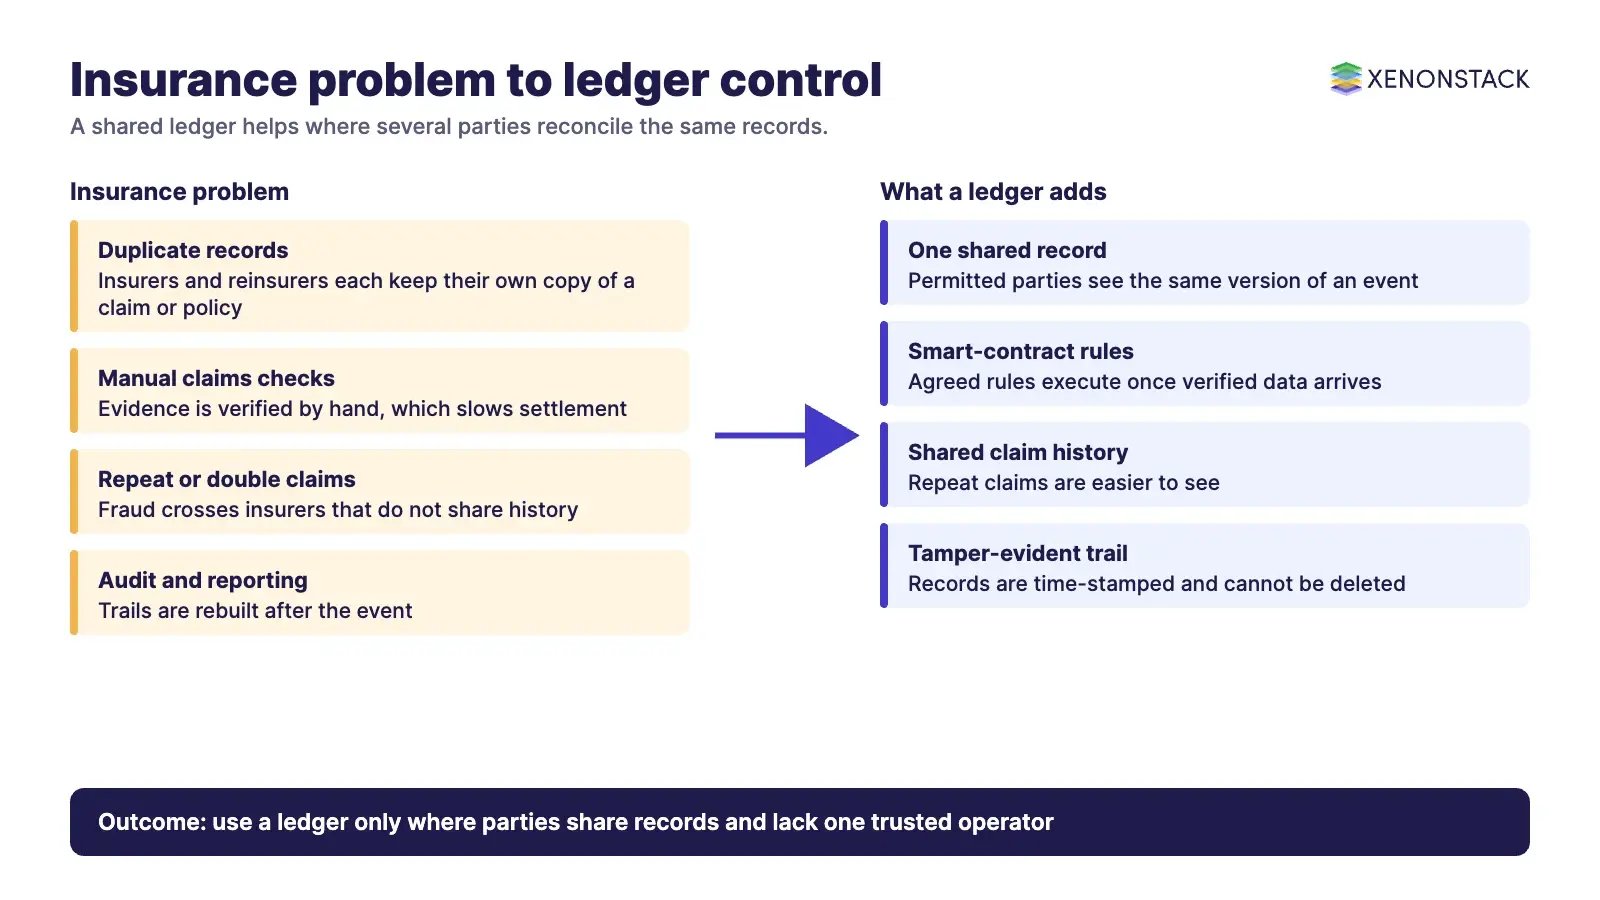
| Pain point | How a ledger can help | What it does not fix |
|---|---|---|
| Duplicate records across insurers and reinsurers | One shared record of a policy or claim event | Data quality at the point of entry |
| Slow, manual claims verification | Smart contracts execute agreed rules once verified data arrives | Disputed or ambiguous claims still need people |
| Fraud such as double claims | Shared claim history makes repeats visible | Fraud committed before data is recorded |
| Audit and regulatory reporting | Time-stamped, tamper-evident trail | Legal interpretation of the policy |
What are the top 10 use cases of blockchain in insurance?
1. Registries of high-value items and warranties
A shared registry can track ownership and claims on high-value items, so a second claim on the same item is easier to spot.
2. Know-your-customer (KYC) and anti-money laundering (AML)
Verified identity records can be shared between organisations with the customer's consent, which reduces repeated checks and duplicate data. Privacy law still decides what may be shared.
3. Parametric insurance
A smart contract pays out when an agreed trigger is met. The NAIC gives the example of parametric crop insurance triggered by verified drought data. The trigger data source must be trusted, because the ledger only records what it is given.
4. Reinsurance
Insurers, reinsurers and brokers can work from one record of a risk or treaty, which shortens reconciliation and eases audit.
5. Distribution of insurance
Policies, premiums and claims from several parties can be coordinated on one platform, which suits marketplaces and embedded products.
6. Fraud detection and risk prevention
Shared claim records across insurers help surface repeated or suspicious claims. Fraud models still need data from outside the ledger.
7. Peer-to-peer insurance
Pooled funds can be held and released under smart-contract rules that every member can inspect.
8. Lower administrative cost
Automated checks on policyholder identity, contract validity and claims registration can remove manual steps. Measure your own baseline, as published savings figures vary by case.
9. Property and casualty insurance
Auto, home and commercial lines involve manual entry. Shared ledgers and smart contracts can issue and settle simple claims with fewer hand-offs.
10. Data collection and secure storage
IoT devices can feed data, for example from wearables in health insurance, to a ledger that analytics then use for pricing. Store only hashes on the ledger and keep personal data off-chain.
Which use case fits which situation, and what is the status?
| Use case | Best fit when | Main caution |
|---|---|---|
| Parametric cover | Trigger is objective and measurable | Reliability of the data feed |
| Reinsurance records | Many counterparties share one risk | Network governance and onboarding |
| KYC and AML sharing | Several insurers verify the same customers | Privacy law and consent |
| Claims fraud checks | Fraud crosses insurers | Data-sharing agreements |
| Peer-to-peer pools | Small groups need transparent rules | Legal status of the pool |
The NAIC states that blockchain applications are not currently widely used in the insurance industry, so expect pilots and consortium projects rather than mature, off-the-shelf products. ElixirData Context OS keeps governed context, versioned policy and decision traces in one decision layer above AI agents, which helps when ledger data feeds automated underwriting or claims decisions.
What are the limits and risks?
Immutability cuts both ways. NIST notes a published transaction cannot be changed under normal operation, so a wrong entry stays and must be corrected by a later entry. Plan for corrections.
Privacy. Public chains expose data. Use permissioned networks, keep personal data off-chain and check data protection rules for your markets.
Security. The ledger is only one layer. Keys, smart-contract code and connected systems are still attack surfaces, so review them like any other application. See our blockchain in cybersecurity guide.
Cost and adoption. A ledger needs partners to join it. Without them, a conventional shared database is cheaper and simpler.
Regulation. Confirm with your regulator how smart-contract payouts and shared records fit local insurance rules before launch.
How should an insurer start?
Pick one process where several organisations already reconcile records, such as reinsurance bordereaux or claims checks.
Ask whether a shared database with access control would do. Use a ledger only where parties do not trust a single operator.
Agree governance, data standards and who runs nodes with partners first.
Run a pilot with measurable targets for cycle time and error rates, and keep personal data off-chain.
Link the outputs to your analytics and decision systems. See data analytics in insurance for the data side.
To map one insurance decision your AI agents should make, and the context and policy it depends on, book a Context Workshop. See what happens in the workshop.
Frequently asked questions
Is blockchain widely used in insurance?
The NAIC states that blockchain applications are not currently widely used in the insurance industry. Most activity is in pilots and consortium projects.
What is a smart contract in insurance?
The NAIC describes a smart contract as a decision executed by a computer algorithm on a blockchain, which cannot be changed by either counterparty once in effect. In insurance it can pay a claim when an agreed trigger is verified.
Can blockchain stop insurance fraud?
It cannot stop fraud entered at source, but permanent shared records make repeated or inconsistent claims easier to see. The NAIC links permanent records to audit trails and fraud reduction.
Does immutability create problems?
Yes. NIST says a published transaction cannot be changed under normal operation, so errors are corrected with later entries, and personal data should stay off-chain.
When is a normal database better?
When one organisation can run the system, or partners will not join a shared network, a database with access control is simpler and cheaper.
Related reading
Follow XenonStack on LinkedIn: XenonStack on LinkedIn for new guides on agentic AI, data and platform engineering.
Ready to put AI agents to work? Explore ElixirClaw, the agentic OS platform to build, orchestrate and govern AI agents.
Explore the XenonStack platform family: ElixirData · ElixirClaw · ElixirHub · NexaStack · MetaSecure · Neural AI · AgentGRC · AgentSRE · AgentAnalyst · AgentInstruct · AgentRAI · AgentScrum · AgentSearch · AgentForce · AI Aviator · SAIF Aviator · CohortIQ · XenonStack AI · XenonStack UAE