Key takeaway
- Agentic AI in insurance claims: which tasks suit agents, NAIC AI bulletin and EU AI Act rules, governance, cost and a step-by-step adoption sequence.
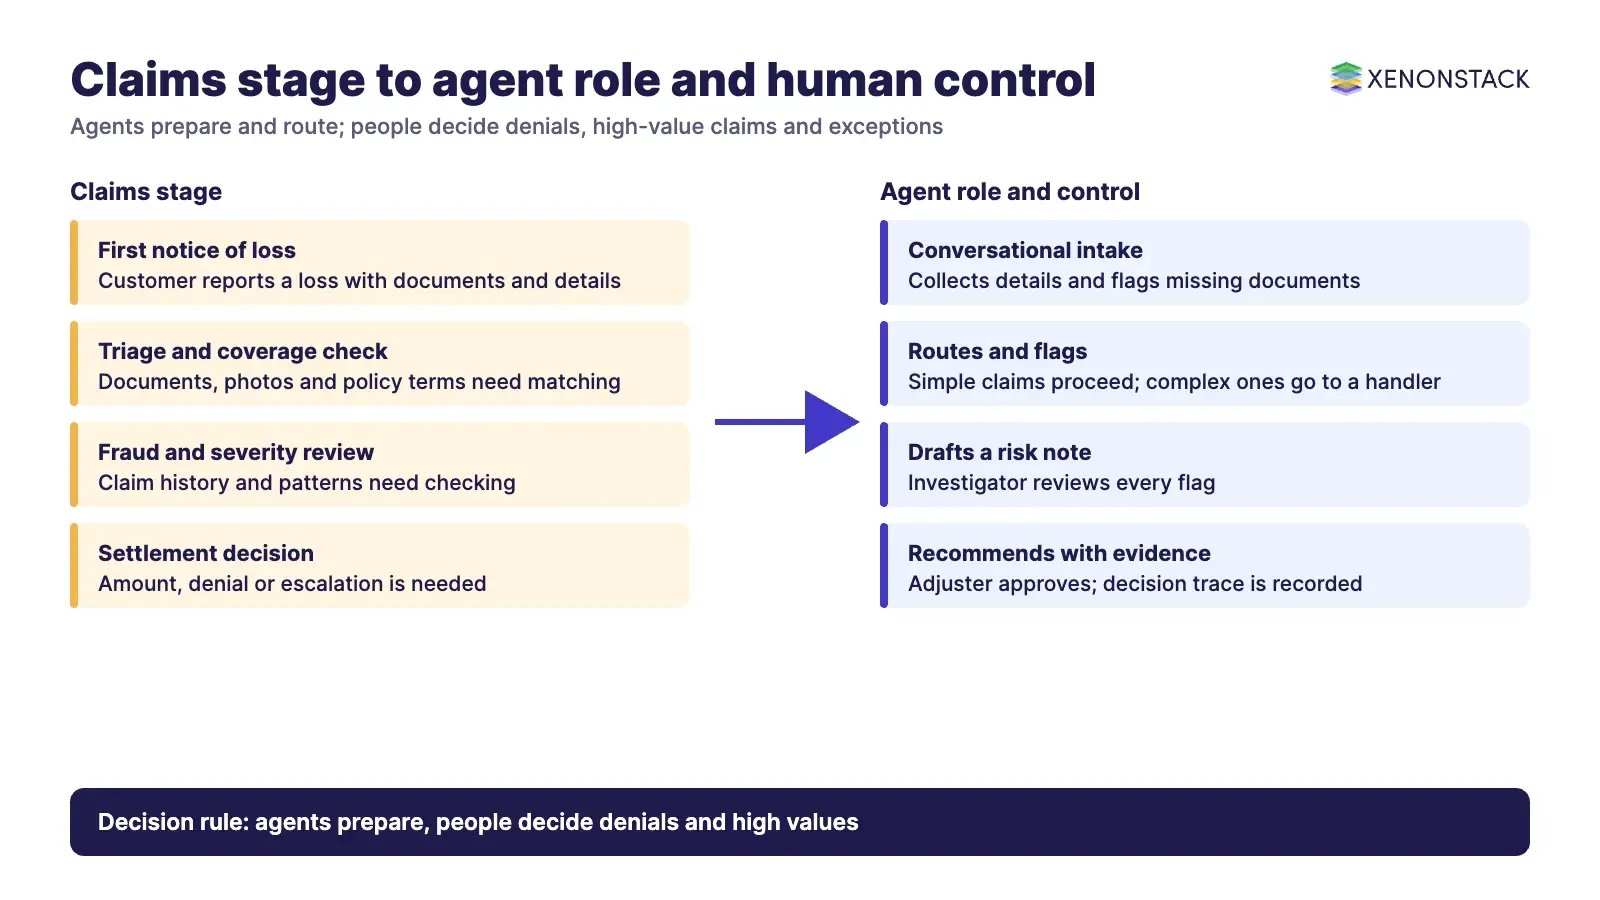
Agentic AI in insurance claims means software agents that read a claim, check it against the policy, run fraud and severity checks, and draft or route a decision, while people keep authority over denials, high-value claims and exceptions. The sound pattern for 2026 is narrow agents with defined limits, a human approval step and a full record of why each decision was made, not a single autonomous system that pays claims on its own.
For CIOs, heads of claims and enterprise architects, the question is where agents earn their place first and what controls regulators expect. This guide covers the claims tasks that fit agents, what has changed in US and EU rules, the governance and cost points, a sequence for adoption and when not to automate. It sits beside our guides to agentic process automation in insurance and data analytics in insurance, and focuses on the claims lifecycle itself.
What is agentic AI in insurance claims?
Agentic AI describes systems that pursue a goal by planning steps, using tools and adjusting to feedback, rather than answering one prompt at a time. In claims, that means an agent that gathers documents, queries policy and claims systems, scores the claim and prepares a recommendation. Rule-based automation follows a fixed script and stops when a case does not fit it. An agent can handle more variation, but it needs limits on what it may decide and a person to take the cases it cannot.
| Claims stage | What an agent does | Who decides |
|---|---|---|
| First notice of loss | Conversational intake collects details, checks for missing documents and tells the customer what is still needed | Agent, within a defined checklist |
| Triage and coverage check | Reads documents and photos, matches the loss to policy terms, routes simple claims and flags complex ones | Agent for simple cases; handler for the rest |
| Fraud and severity review | Runs anomaly and pattern checks against claim history and drafts a risk note | Investigator reviews every flag |
| Settlement recommendation | Drafts an amount and rationale with the evidence used | Adjuster approves, especially for denials and high values |
| Payment and closure | Produces documents, schedules repairs or payment, updates records | Agent, under approval rules |
Where does traditional claims handling slow down?
Manual claims work tends to stall in four places. Documents arrive incomplete, so bills, reports or proof of loss are chased by email. Information entered at purchase or filing is wrong, which triggers rejections and rework. Customers file late, which makes investigation harder. And every check depends on a person reading a file, so turnaround follows queue length. Each of these is a data and routing problem before it is a model problem, which is why agents that gather and validate information are often the first to pay back.
Which claims tasks suit agents, and which do not?
| Task | When it fits | Control to keep |
|---|---|---|
| Claims assistant (intake) | High volume of routine claims with predictable documents | Clear handover to a person on request |
| Document and image triage | Photos, invoices and reports in many formats | Sampled human checks of extraction accuracy |
| Coverage and eligibility check | Policy terms held in structured, versioned form | Link each result to the policy clause used |
| Fraud and anomaly detection | Enough history to learn normal patterns | Humans review flags; no automatic denial |
| Device and sensor-based notices | Connected vehicles or homes that report damage events | Consent, data minimisation and clear fallbacks |
| Denials and complex or high-value claims | Rarely suitable for full automation | Adjuster decision with the agent's evidence attached |
For intake, triage and exception routing, ElixirData's Exception Handling Agent flags cases that need a person's decision, assembles their context and precedents, routes them to the right authority and records each resolution in an auditable trace. ElixirClaw describes its approach to claim processing with autonomous agents as specialised agents that process simple claims automatically and flag complex ones for investigation.
What has changed for insurers in 2026?
Regulation is now the main design input. In the US, the NAIC Model Bulletin on the use of AI systems by insurers was adopted on 4 December 2023, and the NAIC adoption map dated 3 November 2026 lists 29 jurisdictions that have adopted it (27 states, the District of Columbia and Puerto Rico). Its programme guidance names claims directly: the written AI programme should cover use across the life cycle, including case management, claim administration and payment, and fraud detection. In the EU, Annex III of the AI Act classes AI for risk assessment and pricing in life and health insurance as high risk but does not list claims handling. The AI Omnibus entered into force on 27 July 2026, and Annex III obligations now apply from 2 December 2027.
McKinsey's July 2026 paper on how AI will reshape insurance economics treats claims accuracy (reserving, early problem detection and settlement decisions) as a structural priority that AI strengthens, and asks leaders how they are reimagining claims management as a driver of loss ratio and customer experience. It does not publish claims cost or cycle-time reductions, so treat any single percentage quoted for claims automation with caution unless it names its method and sample.
| Rule or source | What it says | Status |
|---|---|---|
| NAIC Model Bulletin | Written AI programme, governance, risk controls and third-party oversight, covering claim administration, payment and fraud detection | Adopted 4 Dec 2023; each state issues its own version |
| NAIC adoption map | 29 jurisdictions listed as adopted; Nebraska is listed as guidance rather than a bulletin | Map dated 3 Nov 2026 |
| EU AI Act, Annex III point 5(c) | Risk assessment and pricing for natural persons in life and health insurance is high risk; claims handling is not listed | Applies from 2 Dec 2027 after the AI Omnibus |
How should governance, security and cost be handled?
The NAIC bulletin expects a written programme that mitigates adverse consumer outcomes, with governance, risk management, internal controls and internal audit, and with senior management accountable to the board or a committee. Controls should be proportionate to the risk to consumers. The programme applies whether the AI system was built by the insurer or a third-party vendor, and insurers should carry out due diligence on vendors and may need contractual audit rights. The bulletin also cites unfair claims settlement practice law, which sets standards for the investigation and disposition of claims, so an agent that delays or denies without a documented reason is a compliance exposure, not only a service issue.
In practice, that points to five design rules. Keep an inventory of every agent and model that touches a claim. Store the policy version, evidence and reasoning behind each recommendation as a decision trace that an auditor can replay. Remove or mask personal data before it reaches a model where the task does not need it. Set approval thresholds by claim value and by outcome type. Track cost per claim handled, including model calls and human review time, so scaling does not hide rising review effort. ElixirData Context OS keeps governed context, versioned policy and decision traces in one decision layer above AI agents, which is the kind of record these rules call for.
In what order should insurers adopt claims agents?
- Assess readiness. Check claims systems, document quality, policy data and the skills of handlers and adjusters.
- Fix the data foundation. Consolidate claims, policy and customer data from legacy systems, and clean and label datasets before agents depend on them.
- Pilot one narrow flow. Start with intake and document triage or fraud flagging on a single product line, with metrics for processing speed, cost per claim and accuracy.
- Add human approval and traces. Put approval rules and decision records in place before widening scope.
- Test for bias and compliance. Audit outcomes regularly and involve legal and compliance teams on privacy law and the state rules above.
- Scale in phases. Extend to coverage checks and settlement recommendations, then to adjacent functions, using feedback loops and KPIs.
- Monitor and retrain. Track performance, drift and exceptions, and update models with fresh data.
Our guide to auto insurance claim prediction with explainable AI covers how to explain model outputs to handlers, customers and regulators, which supports steps four and five.
When should insurers not automate a claim?
- When source documents or policy data are incomplete, because the agent will act on errors at speed.
- When a decision cannot be explained to the policyholder or a regulator.
- When the outcome is a denial, a reduction or a high-value settlement and no person reviews it.
- When the claim involves vulnerable customers, disputed liability or possible litigation, where judgement and empathy matter.
- When a vendor cannot give audit access or evidence of how its model behaves.
To map one claims decision your agents should make, and the context and policy it depends on, book a Context Workshop. See what happens in the workshop. You can also see how ElixirClaw, an agentic OS platform to build, orchestrate and govern AI agents and automation workflows while keeping humans in control, fits a claims programme.
What should you plan for in 2027?
For insurers operating in the EU, one date matters most next year.
- 2 December 2027: the European Commission says Annex III high risk AI requirements apply from this date under the AI Omnibus. Read the Commission news item.
- Annex III point 5(c) covers risk assessment and pricing for natural persons in life and health insurance. Claims handling is not listed on that page. Read Annex III.
- Inventory your agents: list every agent that touches pricing, risk scoring or fraud flags, and confirm with legal advisers whether each falls in scope.
Keep decision traces and human approval for denials and high value claims in the meantime.
Frequently asked questions
What is agentic AI in insurance claims?
It is the use of AI agents that gather documents, check coverage, run fraud and severity checks and draft or route a claim decision within set limits, with people approving denials, high-value claims and exceptions.
Can agents settle claims without a human?
For simple, low-value claims with complete data, an agent can process and pay under approval rules. Denials, complex and high-value claims should have a named person decide, using the agent's evidence.
Does the NAIC bulletin apply to claims?
Yes. Its programme guidance covers AI used across the insurance life cycle, including claim administration and payment and fraud detection, and it applies to vendor-built systems as well as in-house ones.
Is claims handling high risk under the EU AI Act?
Annex III point 5(c) lists risk assessment and pricing for life and health insurance. It does not list claims handling, but fraud and pricing uses may still be caught by other rules, so check each use case.
Where should an insurer start?
Start with one narrow flow such as intake and document triage on one product line, with human approval, decision traces and agreed metrics for speed, cost per claim and accuracy.
What should be logged for each agent decision?
Record the policy version, the evidence used, the model or agent version, the recommendation and the person who approved or overrode it, so the decision can be replayed in an audit.
Follow XenonStack on LinkedIn: XenonStack on LinkedIn for new guides on agentic AI, data and platform engineering.
Explore the XenonStack platform family: ElixirData · ElixirClaw · ElixirHub · NexaStack · MetaSecure · Neural AI · AgentGRC · AgentSRE · AgentAnalyst · AgentInstruct · AgentRAI · AgentScrum · AgentSearch · AgentForce · AI Aviator · SAIF Aviator · CohortIQ · XenonStack AI · XenonStack UAE